
Learn all the details of how financing with ASNEF works throughout this article and find out if it works for your company.
Financing with Asnef
It is the one in charge of registering in a database all the unpaid credits of its associates, so that all entities can access and be aware of the information, which is shared among its members.
The information in the database is not managed by the same association, but by a private company called EQUIFAX, a multinational in the credit risk analysis sector, which sometimes causes confusion, because one might think that there are two databases different data, but it is not.
Operation of the financing list with Asnef
Associates, financial and private entities, report their non-payments to Asnef. This data is made up of companies and institutions such as banks, financial credit establishments, credit cooperatives, mutual guarantee companies, telecommunications, oil companies, credit insurance, book publishers and distributors, office automation, card distributors, telephone operators, energy companies, food companies and securities and stock exchange agencies, among others.
And what can have the characteristics of a financial debt as a commercial debt, in different sectors. Next, we leave you this audiovisual material that explains how to know if we are on the Asnef list.
According to what is established in the Law, before a debtor is included in the data, he must be notified through a letter within 30 days after the request for registration in the data of his non-payment, where the information and file number to consult the details of the debt to either settle it or request its cancellation for any reason. If there is no communication from the debtor, it will be published in Asnef after 90 days.
How to know if my company is on the Asnef list?
There are several ways to know if a company is included in the financing list with Asnef:
- If the debtor received the letter, you can consult the detail of the unpaid debt through this link, indicating the reference number specified in the letter.
- Finally, an informal way to access Asnef data is by requesting information through trusted banks, normally, they will inform you for free, although there is a possibility that they will not provide you with the documentation, since it is not one of the the services they normally provide.

Loan application for companies being on the Asnef list
The content of the list or relationship has a fundamental scope and objective, the consequence of which is a hardening of access to financing for companies, given the existing inter-institutional relationship between the entities that consult Asnef as part of the risk study process and the fact Failure to appear is an essential condition for the operation to be approved.
- If the debt reflected in Asnef is small and is not from a financial institution, it is very possible that the financing possibilities are still feasible, and you will be able to request a new loan under the same conditions as if the company did not appear on the list.
- If the debt that appears in Asnef and is a relevant amount and/or belongs to a financial institution, things get more difficult, but not impossible:
- Promissory note discount and factoring: the company continues to maintain its financing possibilities with the promissory note discount and customer factoring, although through the non-banking circuit.
- Confirming: Whatever the situation of the company, you can always anticipate your charges for confirming, since the credit risk falls on your client and it is the bank that has the line enabled.
The remainder of financial risk products, such as the loan or the credit policy, are practically banned when the company appears on the Asnef list, except in the case that the company can provide very solvent guarantees.
How can I request removal from the Asnef list?
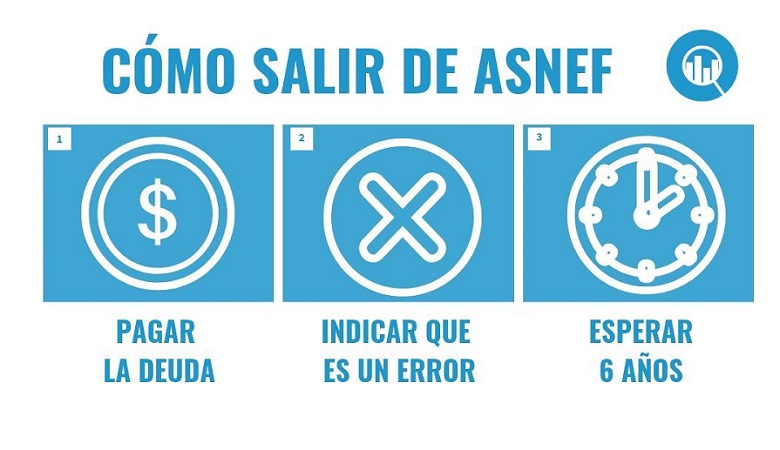
Below we will mention the three ways to unsubscribe from the Financial Credit Institutions list
- Paying the debt: It is the most effective and quickest, paying the debt removes it from the data and takes between 2 and 6 weeks. It is advisable to pay the debt and then start the claim process with the creditor if the debt is not correct.
- Appealing the right to cancel the debt in the registry when it is not correct, following the model provided by the Spanish Agency for Data Protection. It is important to document very well the reasons why the debt should not be registered.
- The stipulated time to remain in the data is 6 years, therefore the registration of the debts in Asnef are cancelled, that is, an unpaid debt cannot be published in Asnef for more than 6 years, which does not imply a prescription of the same.
If the financial market interests you, we invite you to learn more with the following link: Investment Portfolio
Can you delete the data from this list without paying the debt?
It is a rule that as long as the pending obligations are not cancelled, the data of the company or person will not be excluded or eliminated from Asnef. As mentioned above, this incidence can last up to 6 years. In recent years there has been a significant dependence, companies and people on 100% bank loans to finance themselves.
This scenario has changed a lot, with the growth of alternative financial entities and solutions that do not take into account the Asnef so that today it is possible to find financing regardless of whether or not it is included in the data or file.
How long does it take for Asnef to delete me from its delinquent file?
Removing your data from the ASNEF list is quite quick and easy. Your data can be deleted the same day you provide proof of debt cancellation or meet one of the aforementioned requirements. Within a month , no record of your presence on the ASNEF list should remain.
If personal information continues to be reflected in other data or files as delinquent, we must demand the elimination of each one of them, even if it is the company that claims the debt, the one in charge of requesting the elimination of the data.

Know why you can be denied financing
The lack of financing is a great obstacle for many businessmen and entrepreneurs, therefore, it is normal for you to wonder why they can deny you financial support when you request it.
The reasons are very varied, but the level of risk is a key factor; Financial institutions evaluate the applicant's profile and solvency, based on the financial information provided.
Today it is more complex and demanding, because banks impose stricter requirements to grant loans. This breaks the traditional scheme that supported the companies and the degree of reliability that was maintained.